
A property can be gifted to a child, but there’s no automatic tax-free route. According to HM Revenue & Customs, a lifetime gift is exempt from Inheritance Tax only if you survive seven years from the date of the gift. The answer to how to gift property to children tax-free in the UK also depends on Capital Gains Tax, any mortgage and whether you continue living in the property.
Passing a home to your child can feel like a straightforward way to support their future or plan your estate. But transferring ownership can have tax and practical consequences, and giving the property away does not necessarily mean giving up the right to live there.
This article explains the seven-year rule, potential tax costs and what can happen if you continue living in the home. It also covers children’s ability to own property and how trusts may help you plan for that, so you can weigh the options before deciding.
Key Takeaways
- A property gift may affect your estate for years, so understand the inheritance tax rules before transferring ownership.
- Consider whether Capital Gains Tax could apply, particularly if the property is not your main home.
- Keeping the right to live in a gifted home can affect how it is treated for inheritance tax.
- Children’s age can affect how a property is held, making trust arrangements relevant to some families.
- Explore how will writing and trust planning can support your intentions for the property and your family.
What is the 7-year rule for gifting property?
A property gift to an individual may be exempt from Inheritance Tax if the giver survives seven years. Other lifetime gifts, thresholds and tax charges can affect the outcome.
Inheritance Tax and the Seven-Year Rule
Under the seven-year rule, a lifetime gift to an individual is exempt from Inheritance Tax if the giver survives for seven years after making it. This is relevant when parents consider transferring property: the gift date and how long the giver survives affect its treatment. If the giver dies sooner, the gift may be included when working out Inheritance Tax on the estate.
Potentially Exempt Transfers
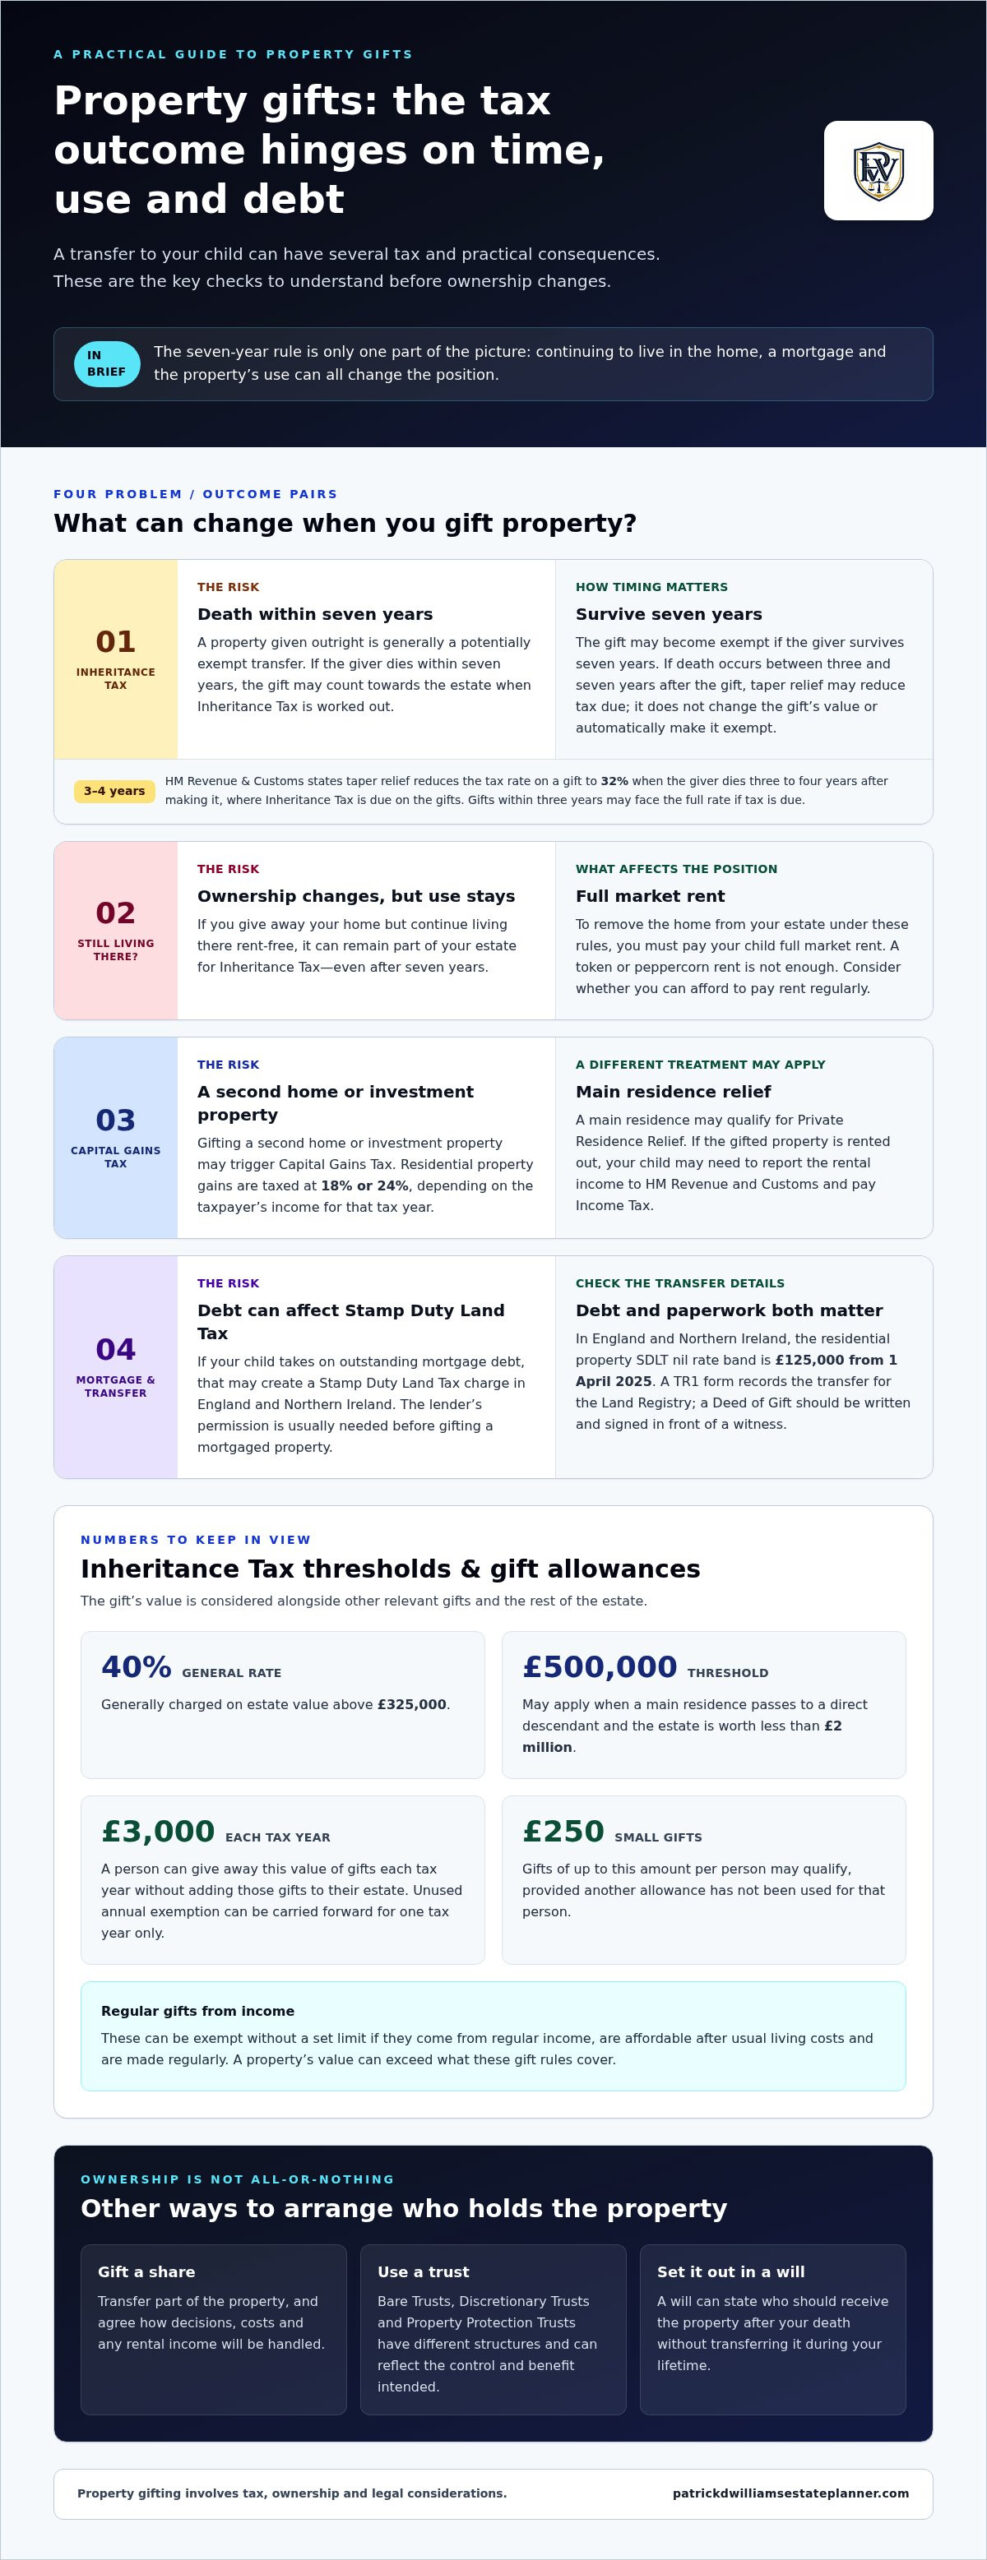
A property given outright to a child is generally treated as a potentially exempt transfer for Inheritance Tax. It becomes exempt if the giver survives seven years, but may count towards the estate if they die sooner. Its value is considered alongside other relevant gifts and the estate, so the transfer date alone does not determine whether Inheritance Tax is due.
Taper Relief on Lifetime Gifts
Taper relief can reduce the tax due on a lifetime gift when the giver dies between three and seven years after gifting. It does not change the gift’s value or automatically make it exempt. According to HM Revenue & Customs, taper relief reduces the tax rate on a gift to 32% when the giver dies three to four years after making it. Relief applies where Inheritance Tax is due on the gifts.
Inheritance Tax is generally charged at 40% on estate value above £325,000, or above £500,000 when a main residence passes to a direct descendant and the estate is worth less than £2 million, according to HM Revenue & Customs. The applicable threshold matters when assessing a gift alongside the remaining estate. Gifts within three years of death may face the full rate if tax is due.
Thresholds, Exemptions and Allowances
Thresholds and gift exemptions determine how much value may be outside an Inheritance Tax charge. A person can give away £3,000 worth of gifts each tax year without adding those gifts to their estate. Unused annual exemption can be carried forward for one tax year only. Small gifts of up to £250 per person may also qualify, provided another allowance has not been used for that person.
Regular gifts from income can be exempt without a set limit if the giver can afford them after usual living costs and makes them from regular income. These rules may help with smaller transfers, but a property’s value can exceed what they cover. The total value of relevant gifts and the estate therefore matters when assessing the likely Inheritance Tax position.
Other taxes may apply independently. HM Revenue & Customs states that residential property gains are taxed at 18% or 24%, depending on the taxpayer’s income for that tax year. In England and Northern Ireland, the residential property SDLT nil rate band is £125,000 from 1 April 2025, according to HM Revenue & Customs. An outstanding mortgage transferred with the property can affect SDLT.
Can I gift a property to my child?
Yes. You can transfer all or part of a property, but the tax and practical effects depend on the mortgage, how you use the home and whether it earns income. If your child takes on outstanding mortgage debt, that may create a Stamp Duty Land Tax charge in England and Northern Ireland. The lender’s permission is usually needed before gifting a mortgaged property.
Gifting a Home You Still Live In
Gifting your home while continuing to live in it means transferring ownership but keeping its use. Living there rent-free can mean the home remains part of your estate for Inheritance Tax, even after seven years. To remove it from your estate under these rules, you must pay your child full market rent. A token or peppercorn rent is not enough. Before transferring the home, consider whether you can afford to pay rent and are willing to do so regularly.
Gifting Holiday Homes and Investment Properties
You can also gift a holiday home or rental property, but its tax treatment may differ from that of your main residence. A gift of a second home or investment property may trigger Capital Gains Tax, while a main residence may qualify for Private Residence Relief. If your child receives rental income, they may need to report it to HM Revenue and Customs and pay Income Tax. Decide who will receive the rent and meet the property costs after the transfer.
Gifting Shares or Using a Trust
You may give your child a share of a property rather than transferring the whole title. This changes the ownership without giving them the entire asset, so agree how decisions, costs and any rental income will be handled. A trust is another way to hold property for a child. Bare Trusts, Discretionary Trusts and Property Protection Trusts have different structures, so consider what control and benefit you intend to pass on.
Alternatives to an Outright Gift
An outright gift transfers ownership to your child, so it may not suit a parent who needs continued control or use. A partial share or trust may better reflect your intentions. Alternatively, a will can set out who should receive your property after your death, without transferring it during your lifetime. A Property Protection Trust is one option to consider when planning how property should be held for family members.
Legal Requirements for a Property Transfer
A property transfer involves formal documents. A TR1 form records the transfer for the Land Registry, and a Deed of Gift should be written and signed in front of a witness. If a mortgage remains, the lender’s permission is usually required. A person acting under a power of attorney should check whether the document allows a property gift and whether making the gift is appropriate. These steps matter because tax planning does not itself complete the legal transfer.
Do I need to pay Capital Gains Tax on gifted property?
A property gift can create Capital Gains Tax (CGT), even if your child pays nothing. The outcome depends on the property’s value, your original cost and any relief available.
Capital Gains Tax on Property Gifts
For CGT, a property given to a child is generally treated as transferred at market value. The gain is worked out by comparing that value with what you paid, then taking account of allowable costs and reliefs. The residential property CGT rates are 18% or 24%, depending on your income for that tax year, according to HM Revenue & Customs.
You may be able to use the £3,000 annual CGT exemption against gains, if you haven’t already used it. Some capital improvement spending and certain purchase or gift costs can also be deducted. Keep records showing the purchase price, improvement work and transfer date, as these details help establish the taxable gain.
Gifts and Below-Market Transfers
Selling a home to your child for a token amount, such as £1, doesn’t necessarily reduce the CGT calculation. A gift or below-market transfer to a child is generally treated as taking place at market value. CGT can therefore arise on the difference between that value and your original purchase cost, even if you receive little or no money.
This can create a tax bill without sale proceeds to pay it. If CGT is payable on a UK property gift, HM Revenue & Customs requires the gift to be reported and the tax paid within 60 days. Check the gain calculation and available exemption before transferring ownership, rather than assuming the stated sale price sets the taxable amount.
Second homes and rental properties may attract CGT when gifted. A main residence may qualify for Private Residence Relief, depending on the circumstances. A gift with reservation of benefit is a separate Inheritance Tax issue: it concerns retaining use or benefit, not how a property gain is calculated for CGT.
Your child’s CGT position may also matter if they sell the property after the transfer. If they do not live there, they may owe CGT on the increase in value since receiving it. Their use of the home and the gain at sale affect the calculation, so record its market value when gifted.
Transfers between spouses are exempt from CGT. This differs from a gift to a child, where market value is generally used. Stamp Duty Land Tax is separate from CGT: in England and Northern Ireland, taking on mortgage debt as part of a gift can affect SDLT, even when the transfer is not a conventional sale.
Gifts with reservation of benefit
A gift with reservation of benefit occurs when you transfer ownership but continue to enjoy the property. For example, if a parent gifts a home but continues living there rent-free, it may still be included in their estate for Inheritance Tax. The seven-year period does not change this treatment while the reservation continues.
If you want to keep living in a gifted home without retaining a benefit under these Inheritance Tax rules, you must pay full market rent. The rent should reflect the property’s market value and be reviewed annually. A peppercorn rent does not end the reservation. Keep records of rent payments and reviews to show the arrangement reflects genuine market rent.
This arrangement has practical implications for ownership and household finances. After the transfer, you must be able to meet the rent payments, while your child becomes the owner. An outstanding mortgage can also affect whether the transfer proceeds, as lender permission is usually required. A solicitor can document the arrangement and explain its legal implications before the property changes hands.
Gifts between spouses or civil partners are exempt from Inheritance Tax if the recipient lives permanently in the UK and the couple are legally married or in a civil partnership. Wedding and civil partnership gifts have separate exemptions: a parent may give a child up to £5,000, a grandparent may give a grandchild up to £2,500, and gifts to other people are limited to £1,000. These exemptions apply to qualifying gifts, not to a home occupied rent-free after transfer.
A parent can combine a qualifying wedding gift with an unused annual gift allowance. For example, a parent may give up to £8,000 by combining a £5,000 wedding gift with an unused £3,000 annual allowance. The annual allowance may be carried forward for one tax year only. These rules concern Inheritance Tax, so they do not by themselves settle any Income Tax due on income from gifted assets.
Income Tax rules also apply to some gifts involving children under 18. If a parent gifts an asset producing net income above £100 per year, that income is taxed on the parent as if they still owned the asset. This rule does not apply to income from gifts made by grandparents. Interest on money gifted to a child may have tax implications for the parent.
If your child receives rent from gifted property, they may need to report that income to HM Revenue and Customs and pay Income Tax. The source of the gift and who receives the income matter. Distinguishing rent from a gifted home, interest on gifted money and income from a grandparent’s gift helps identify the relevant tax treatment.
Children’s legal capacity to own property and trust arrangements
In the UK, a child under 18 generally cannot own land or property in their own name. In Scotland, the age is under 16 in some circumstances. This creates a practical issue for parents planning a direct transfer: the child cannot simply be registered as the legal owner while below the relevant age. A trust can provide an alternative way to hold property for them.
With a trust, trustees hold the legal title and manage the property for the beneficiary under the trust’s terms. Those terms should reflect the family’s aims, including who may benefit, who makes decisions and how the property will be managed. For example, a parent might want a child to benefit from a home later while responsible adults manage it in the meantime. The trust deed sets out the arrangement.
Trusts are not interchangeable. Bare Trusts, Discretionary Trusts and Property Protection Trusts can involve different arrangements for control and benefit. The appropriate structure depends on your circumstances, the child’s needs and how much control you want to retain. Consider who would make decisions about repairs, occupation or sale, and who would receive any rental income.
Tax implications also matter. A gift of property into a trust may face an immediate Inheritance Tax charge of 20% if its value exceeds the available nil-rate band of £325,000. That is different from an outright gift to an individual, so the transfer route can affect when tax is charged. A trust does not automatically make property tax-free, and the property’s value and terms of the arrangement are important.
Putting a property into a trust can also have Capital Gains Tax implications. A trust changes how the property is held, but you still need to consider its tax treatment when it is transferred and if it is sold later. Consider the intended beneficiary, trustees’ powers and any mortgage together. If there is a mortgage, the lender’s permission may be needed before ownership is transferred.
Before settling on a trust, set out who should benefit and who should manage the property. Then consider the legal documents, tax implications and practical responsibilities as one plan. This helps parents compare a trust with an outright gift or leaving the property through a will. Discuss trust planning for a child as part of deciding how the property should be held.
Patrick D Williams Estate Planners: Will Writing
Patrick D Williams Estate Planners can help you consider how a property gift fits into your wider estate plan. Its Will Writing service can record how you intend your estate to pass. A Property Protection Trust, Discretionary Trust or Bare Trust may be relevant when deciding how to hold property for family members. Lasting Powers of Attorney can also form part of planning for decisions if you become unable to make them yourself.
Consider tailored estate planning when weighing an outright gift against keeping ownership or using a trust. The right arrangements depend on your intentions, family circumstances and the role the property plays in your estate.
Contact Patrick D Williams Estate Planners to discuss your property and estate planning needs.
Make your property intentions part of a wider plan
A decision about a home affects more than who owns it. It can shape where you live, how your family benefits and what choices remain available later. Before taking action, consider the outcome you want for your child alongside your own need for security and flexibility. Looking at the bigger picture can help you decide whether a lifetime transfer belongs in your estate plan.
Planning how to gift property to children tax-free in the UK means considering the legal structure and tax effects together, rather than treating the transfer as an isolated transaction. Your family circumstances and how you use the property both matter. A carefully prepared plan can set out your intentions and give your family clearer guidance.
Patrick D Williams Estate Planners can help you consider how estate planning fits your wishes. Contact Patrick D Williams Estate Planners to discuss your next steps and make a considered plan for your family’s future.
Frequently Asked Questions
Do you pay stamp duty on gifted property?
Usually, no Stamp Duty Land Tax (SDLT) is charged on a gift in England and Northern Ireland if no mortgage debt transfers. If your child takes responsibility for an outstanding mortgage, that debt can count as consideration and create an SDLT charge. The tax relates to the chargeable amount, not simply the fact that the home is a gift. Scotland and Wales have separate property transaction taxes.
Can I give my house to my children?
Yes, you can give your child all or a share of your home. If they’re under 18, they generally cannot hold legal title themselves, so a trust may be used to hold it for them. Before transferring ownership, consider any mortgage, who will occupy the property and whether you may need control or proceeds later. Giving the home away can limit your say over what happens to it.
Can I give my son or daughter £20,000?
Yes, a parent can give a son or daughter £20,000 or more. The amount alone does not make the gift automatically exempt from Inheritance Tax. A cash gift to an individual is generally treated as a potentially exempt transfer, so the seven-year period and the giver’s wider estate matter. The £3,000 annual gift exemption may cover part of the gifts, but it does not automatically exempt the full £20,000.
Can I transfer ownership of the family home to my children to avoid paying tax?
You can transfer the family home, but the transfer alone does not remove every tax consequence. If you continue living there without paying full market rent, gift-with-reservation rules can keep its value in your estate. The transfer may also have Capital Gains Tax or mortgage-related SDLT implications. Your child becomes the owner and may choose to sell, so consider your future use and control of the home before gifting it.
What are the tax rules for larger gifts?
A larger gift to an individual is generally treated as potentially exempt for Inheritance Tax, with seven years required for full exemption. Gifts made within that period are considered alongside the estate and relevant thresholds. The £3,000 annual exemption can be used against gifts, with unused allowance carried forward for one tax year. Taper relief concerns tax due on qualifying gifts; it does not make every large transfer exempt.
What is CGT annual exemption?
The Capital Gains Tax annual exemption is the amount of gain that can be realised before CGT applies, subject to the relevant rules. For residential property, it is £3,000 of gain if you have not already used it. The exemption applies to the gain, not the property’s market value. For a gift, work out the gain using the property’s market value at transfer and allowable costs.
Can I gift a property to my children without paying tax in the UK?
Whether you can gift a property to your children tax-free in the UK depends on the circumstances. There is no single way to make every property gift tax-free. Inheritance Tax treatment can depend on how long you live after the gift and whether you retain use of the home. Capital Gains Tax may apply to a second home or investment property, while mortgage debt can affect SDLT in England and Northern Ireland.
What are the UK inheritance tax rules for gifting a house to children?
For parents considering how to gift property to children tax-free in the UK, Inheritance Tax treatment is an important part of the decision. A house given to a child is generally treated as a potentially exempt transfer. It can become exempt if the giver survives seven years, but continuing to benefit from it by living there rent-free can affect that treatment. Gifts made within seven years are considered alongside the estate when calculating tax.
Leave a Reply